by Lorena Cano | Oct 2, 2026 | Uncategorized
Home prices are one of the most visible parts of the housing market, but the number attached to a property does not tell the entire story. Buyers and sellers can benefit from looking at the factors that influence pricing and understanding how local conditions affect property values.
A home’s price can be influenced by location, property condition, size, recent comparable sales, available inventory, buyer demand, and broader economic conditions. These factors can change over time, which is why a property’s value should be considered within its current market context.
Location Can Influence Value
Location remains an important part of residential real estate pricing. Access to transportation, local services, employment centers, parks, shopping areas, and other community amenities can affect how properties are valued.
However, location is only one part of the picture. Two properties in the same general area can have different values because of their size, condition, layout, updates, lot characteristics, and other property-specific factors.
Inventory Can Affect Pricing
The amount of available housing can influence market conditions. When fewer properties are available, buyers may have fewer choices. When inventory increases, buyers may have more opportunities to compare properties and negotiate.
Inventory can also vary by price range and property type. Looking at overall market statistics without considering these differences may provide an incomplete picture.
Comparable Sales Provide Useful Context
Recent comparable sales can help establish a clearer picture of what buyers have actually paid for similar properties. Comparable properties are typically evaluated based on factors such as location, size, condition, features, and timing.
Because no two homes are exactly alike, comparable sales should be considered alongside property-specific characteristics rather than treated as a simple formula.
Market Conditions Can Change
Home prices can move differently from one market to another. National trends may provide useful background, but local supply, demand, economic activity, and housing characteristics can produce different results.
This is why homeowners considering a sale or buyers evaluating a purchase may benefit from looking at current local data rather than relying only on national headlines.
Look at the Complete Housing Picture
Understanding home prices requires more than checking a listing price or a national median. Buyers and sellers can benefit from considering recent sales, inventory, property condition, financing costs, and local market activity together.
A clear understanding of these factors can make it easier to evaluate a property’s asking price and understand how current market conditions may affect a real estate decision.
by Lorena Cano | Sep 29, 2026 | Uncategorized
Fall can be a practical time to focus on home improvements that make a property more comfortable, functional, and prepared for the months ahead. As temperatures begin to change, homeowners can use the season as an opportunity to address maintenance needs, improve indoor comfort, and complete smaller projects before winter arrives.
Home improvement does not always require a major renovation. Simple updates can make everyday living easier while helping a home remain well maintained throughout the changing seasons.
Start With Seasonal Maintenance
Fall is a good time to look closely at areas of the home that may need attention before colder weather arrives. Check for peeling exterior paint, damaged siding, worn weatherstripping, clogged gutters, drafty windows, or areas where moisture may enter the home.
Addressing these issues early can help prevent minor maintenance concerns from becoming more expensive problems. A seasonal inspection can also help homeowners identify projects that should be completed before winter weather makes exterior work more difficult.
Improve Indoor Comfort
As outdoor temperatures become cooler, improvements that support indoor comfort can become especially useful. Sealing drafts around windows and doors, improving insulation where appropriate, updating lighting, and servicing heating equipment can help create a more comfortable living environment.
Small interior updates can also make a noticeable difference. Fresh paint, updated fixtures, improved storage, or new flooring can refresh frequently used spaces without requiring a full renovation.
Refresh Entryways and Outdoor Spaces
The transition into fall can also be a good time to improve areas that connect the home with the outdoors. A clean and organized entryway, repaired steps, updated exterior lighting, or refreshed landscaping can improve the property’s overall appearance.
Outdoor areas should also be checked for seasonal maintenance needs. Cleaning patios and decks, removing leaves and debris, and inspecting outdoor structures can help keep these spaces in good condition as temperatures continue to drop.
Consider Energy-Efficient Improvements
Fall is also a useful time to evaluate how efficiently a home handles changing temperatures. Improvements such as weatherstripping, insulation, energy-efficient lighting, and updated windows may help reduce drafts and improve indoor comfort.
Before making a significant upgrade, homeowners should consider the project’s cost, expected benefits, and suitability for the property. For electrical, plumbing, structural, or heating and cooling work, professional guidance may be appropriate.
Prepare the Home for Winter
Some fall improvements are less about appearance and more about preparation. Checking heating systems, inspecting fireplaces and chimneys where applicable, protecting outdoor plumbing, and making sure exterior drainage is working properly can help homeowners prepare for colder weather.
Completing these projects during the fall may make seasonal maintenance more manageable and give homeowners time to address issues before winter conditions arrive.
Keep Future Resale in Mind
If selling the home is part of a longer-term plan, fall improvements can also help maintain the property’s overall condition and presentation. Well-maintained exterior areas, functional systems, clean finishes, and updated spaces can contribute to how a home is viewed by future buyers.
However, homeowners do not need to undertake major renovations simply because they may eventually sell. Improvements should make sense for the property, the budget, and the homeowner’s plans.
Make a Fall Improvement Plan
A successful home improvement project starts with realistic planning. Identify the areas that need attention, establish a budget, research materials, and allow room for unexpected expenses or delays.
Fall offers a natural opportunity to prepare a home for the season ahead while making practical improvements that can enhance everyday living. Whether the project involves seasonal maintenance, a small interior update, or a larger improvement, thoughtful planning can help keep a home comfortable, functional, and well maintained throughout the year.
by Lorena Cano | Sep 25, 2026 | Uncategorized
The economy plays an important role in the real estate market. Changes in inflation, employment, interest rates, consumer confidence, and overall economic activity can influence home prices, borrowing costs, buyer demand, and investment decisions.
Understanding these economic factors can help buyers, sellers, homeowners, and investors better understand changing housing market conditions.
Mortgage Rates and the Economy
Mortgage rates are closely connected to broader financial and economic conditions. Changes in interest rates can affect monthly mortgage payments and the amount buyers can comfortably finance.
For buyers, understanding current financing costs can be more useful than relying on predictions about where rates may go next.
Inflation and Housing Costs
Inflation can affect both the cost of purchasing a home and the ongoing expenses of homeownership. Construction materials, labor, insurance, maintenance, and other services can become more expensive as overall costs rise.
These changes can influence housing affordability and the expenses associated with owning and maintaining a property.
Employment and Housing Demand
Employment conditions can also influence real estate activity. When employment remains stable, consumers may have greater confidence in making major financial commitments. Changes in employment can affect household budgets and housing decisions.
However, economic conditions can vary across markets, so local data remains important when evaluating real estate activity.
Consumer Confidence Matters
Consumer confidence can influence whether people decide to buy, sell, or invest in real estate. When economic uncertainty increases, some consumers may take more time to evaluate their finances before making a major purchase.
As conditions change, buyers and sellers can benefit from focusing on their individual financial circumstances rather than reacting solely to market headlines.
What the Economy Means for Real Estate Investors
Investors often monitor economic indicators when evaluating potential properties. Interest rates, rental demand, operating costs, property values, and broader economic activity can all affect investment decisions.
Careful financial analysis can help investors understand potential income, expenses, and risks before committing to a property.
Looking Ahead
Economic conditions can change throughout the year. No single indicator provides a complete picture of the real estate market, which is why reviewing multiple factors can provide better context.
Final Thoughts
The economy and real estate market are closely connected. Mortgage rates, inflation, employment, consumer confidence, and operating costs can all influence housing activity in different ways.
By staying informed and reviewing current financial and market data, buyers, sellers, homeowners, and investors can make more informed real estate decisions in 2026.
by Lorena Cano | Sep 24, 2026 | Uncategorized
A clear investment strategy can help real estate investors make more informed decisions in a changing market. In 2026, factors such as financing costs, property values, rental income, operating expenses, and market conditions can all influence an investment’s potential performance.
Define Your Investment Goals
Before purchasing a property, consider what you want the investment to accomplish. Some investors may focus on rental income, long-term appreciation, portfolio diversification, or a combination of objectives.
A defined goal makes it easier to evaluate properties and determine whether an opportunity fits your overall financial strategy.
Evaluate the Complete Financial Picture
Purchase price is only one part of an investment property’s cost. Investors should consider mortgage payments, property taxes, insurance, maintenance, management fees, utilities, and potential vacancy periods.
Estimating both expected income and ongoing expenses can provide a clearer picture of potential cash flow.
Consider Financing Carefully
Mortgage rates and loan terms can significantly affect investment costs. Investors should compare financing options and understand how interest rates, down payments, loan terms, and closing costs may affect their investment strategy.
A realistic financial analysis should account for potential changes in borrowing costs and property expenses.
Research the Market
Market research is an important part of investment planning. Investors can review property values, rental activity, inventory, development, employment trends, and other relevant economic indicators.
Current, property-specific data can be more useful than relying solely on broad market predictions.
Plan for Risk
Every real estate investment carries some level of risk. Rental income may fluctuate, expenses can increase, and property values can change over time.
Maintaining appropriate financial reserves and avoiding assumptions about guaranteed returns can help investors prepare for unexpected changes.
Think About the Long Term
Real estate investments often require a long-term perspective. Investors should consider how a property may fit into their financial plans over several years rather than focusing only on short-term market movements.
Regularly reviewing the investment’s performance can also help determine whether adjustments are needed.
Final Thoughts
A strong real estate investment strategy starts with clear goals, careful financial analysis, market research, and realistic risk management. By evaluating the complete financial picture and staying informed about changing market conditions, investors can make decisions that align with their individual investment objectives.
by Lorena Cano | Sep 22, 2026 | Uncategorized
Real estate investing continues to be an important consideration for people looking to build long-term wealth and diversify their financial portfolios. In 2026, investors are paying close attention to property prices, mortgage rates, rental income, operating expenses, and changing market conditions before making investment decisions.
Start With a Clear Investment Strategy
Before purchasing an investment property, it is important to understand your goals. Some investors focus on rental income, while others may prioritize long-term appreciation, property improvements, or portfolio diversification.
Having a clear strategy can help determine which property types, financing options, and investment approaches may fit your financial objectives.
Understand the Numbers
Successful real estate investing requires more than looking at a property’s purchase price. Investors should consider potential rental income, mortgage payments, property taxes, insurance, maintenance, management costs, vacancies, and other operating expenses.
Reviewing these numbers before purchasing can provide a more realistic picture of potential cash flow and overall investment performance.
Consider Financing Costs
Mortgage rates can significantly affect the cost of financing an investment property. Changes in interest rates can influence monthly payments, cash flow, and the amount of capital required for a purchase.
Investors should compare available financing options and consider how different loan terms could affect the long-term cost of the investment.
Location and Property Fundamentals Matter
Location remains an important factor in real estate investing. Investors can research employment trends, transportation access, development activity, property taxes, rental demand, inventory, and other local market fundamentals.
Rather than relying on general market headlines, reviewing current data for the specific property and market can lead to better-informed decisions.
Plan for Ongoing Expenses
Owning an investment property comes with continuing responsibilities. Repairs, maintenance, insurance, property management, utilities, taxes, and periods of vacancy can affect profitability.
Building an appropriate reserve for unexpected expenses can help investors manage changes in operating costs without disrupting their broader financial plans.
Think Long Term
Real estate investing can involve high upfront costs and may require patience. Market conditions can change, and property values and rental income are not guaranteed to increase.
Investors should evaluate potential risks, understand their financing obligations, and consider whether a property aligns with their long-term financial strategy.
Final Thoughts
Real estate investing requires careful research, realistic financial projections, and an understanding of both opportunities and risks. By evaluating property fundamentals, financing costs, operating expenses, and long-term objectives, investors can make more informed decisions in today’s changing market.
by Lorena Cano | Sep 17, 2026 | Uncategorized
Setting clear real estate goals for 2026 can make buying, selling, investing, or simply preparing for a future move easier to manage. Instead of reacting to changing headlines, a well-defined plan can help you focus on your finances, property needs, and current market conditions.
Whether your goal is to purchase a home, sell a property, build equity, or prepare for a future transaction, understanding what you want to accomplish is the first step.
Start With a Clear Real Estate Goal
Every real estate decision starts with a specific objective. You may be planning to buy a home, sell an existing property, purchase an investment property, or evaluate your current home’s value.
A clear goal makes it easier to determine what information you need and what steps to take next. It can also help you avoid making decisions based only on short-term market changes.
Review Your Financial Position
Your financial position plays an important role in reaching a real estate goal. Buyers should review their income, savings, credit profile, available funds, and potential financing options before beginning a property search.
It is also important to consider the complete cost of ownership. Mortgage payments are only one expense. Property taxes, insurance, maintenance, HOA fees when applicable, and other ongoing costs can affect the overall budget.
For sellers, reviewing the property’s current value, outstanding loan balance, potential selling expenses, and expected proceeds can help establish realistic expectations.
Understand Current Market Conditions
Real estate markets can change throughout the year. Home prices, inventory, mortgage rates, buyer demand, and days on market can all influence a real estate decision.
Rather than relying only on national headlines, review current market data that applies to the properties and price ranges you are considering. Recent comparable sales and active listings can provide useful context when evaluating pricing.
Consider Your Property Needs
Once your financial position and market conditions are clearer, consider what you need from a property.
Factors such as property type, size, condition, location, features, maintenance requirements, and overall ownership costs can help narrow your options.
Keeping the focus on objective property characteristics can make the search more efficient and help you compare properties based on factors that directly affect your decision.
Set a Realistic Timeline
Real estate goals do not always need to happen immediately. Some goals may require months of preparation, while others may be several years away.
Creating a timeline can help you determine when to review financing, monitor market activity, prepare a property for sale, or begin researching available properties.
A realistic timeline also gives you flexibility if market conditions or personal financial circumstances change.
Review Your Goal Regularly
A real estate goal should not be treated as a one-time decision. Mortgage rates, inventory, home prices, financing options, and property values can change over time.
Reviewing your plan periodically can help you determine whether your budget, timeline, and expectations still make sense.
For sellers, this may mean reviewing current comparable sales and competing listings. For buyers, it may mean reassessing financing options and available inventory.
Plan With the Long Term in Mind
Real estate decisions often involve significant financial commitments, so looking beyond today’s headlines can be valuable.
A strong plan considers affordability, property characteristics, market conditions, financing, and potential future expenses. The goal is not necessarily to predict exactly what the market will do, but to make a decision that fits your financial circumstances and objectives.
Turn Your Real Estate Goal Into a Plan
The best real estate goals are specific, realistic, and supported by current information. Whether you are preparing to buy, considering a sale, evaluating your property value, or planning for a future move, having a clear strategy can make the process easier to navigate.
In 2026, understanding your goal and the market conditions around it can help you make a more informed real estate decision.
by Lorena Cano | Sep 15, 2026 | Uncategorized
Owning a home is a long-term commitment that involves more than making a monthly mortgage payment. Regular maintenance, thoughtful improvements, and careful financial planning can help protect your property’s condition and value over time.
Whether you have recently purchased a home or have owned one for years, a proactive approach can help you avoid unnecessary expenses and make better decisions about your property.
Stay Ahead of Home Maintenance
Small maintenance problems can become costly repairs when they are ignored. Regularly check your roof, gutters, plumbing, HVAC system, windows, appliances, and exterior areas.
Creating a seasonal maintenance routine can help you identify potential problems early and keep your home operating efficiently.
Understand Your Home’s Value
Home values can change as market conditions shift. Recent comparable sales, inventory, property condition, and improvements can all influence what a home may be worth.
Reviewing your home’s value periodically can be helpful if you are considering refinancing, selling, renovating, or simply tracking your long-term investment.
Make Improvements With Purpose
Home improvements should balance cost, functionality, and potential value. Before starting a major renovation, consider the project’s expected benefits and how much it will cost.
Updates such as fresh paint, improved lighting, updated flooring, kitchen or bathroom improvements, and energy-efficient features can enhance a home’s functionality and appeal.
Keep Homeownership Costs in Mind
The cost of owning a home goes beyond the mortgage. Property taxes, insurance, utilities, maintenance, repairs, and unexpected expenses should all be considered when planning your budget.
Reviewing these costs regularly can help you prepare for future expenses and avoid financial surprises.
Consider Energy Efficiency
Energy-efficient improvements can reduce operating costs while improving comfort. Depending on the home, upgrades such as better insulation, efficient windows, LED lighting, smart thermostats, and updated HVAC equipment may provide long-term benefits.
Before making an investment, compare the upfront cost with potential savings over time.
Keep Important Records Organized
Keep records of major repairs, renovations, warranties, inspections, permits, and service work. Organized documentation can make future maintenance easier and provide useful information when refinancing or selling.
Digital copies can also make important property records easier to access when needed.
Review Your Insurance Coverage
Your home and its contents can change over time, so it is worth reviewing your insurance coverage periodically. Major renovations, new belongings, or changes to the property may affect your coverage needs.
Discuss your policy with your insurance professional to make sure your coverage remains appropriate.
Stay Informed About the Market
Understanding broader real estate trends can help homeowners make more informed financial decisions. Mortgage rates, home prices, inventory, and economic conditions can all influence the housing market.
However, market conditions can change, so avoid making major decisions based on a single headline or short-term trend.
Plan Before Making Major Decisions
Whether you are considering a renovation, refinancing, selling, or simply maintaining your property, start with reliable information.
Compare costs, consider your long-term goals, and seek professional advice when needed. A thoughtful approach can help you make decisions that support both your home and your finances.
Final Thoughts
Successful homeownership is built on consistent maintenance, smart planning, and informed decisions. By taking care of your property, managing expenses, and understanding its value, you can help protect one of your most important assets.
Small steps today can make homeownership easier and more manageable over the years.
by Lorena Cano | Sep 11, 2026 | Uncategorized
Home prices remain one of the most important factors for anyone considering a real estate move in 2026.
While national housing trends can provide helpful context, local home prices tell a much more relevant story. Pricing can vary significantly based on property type, location, condition, size, features, and current competition.
For buyers and sellers, understanding what is happening in the local market can provide a clearer picture of today’s opportunities.
Home Price Growth Has Moderated
The rapid price increases seen in some earlier periods have eased in many markets.
National forecasts for 2026 generally point toward more moderate price growth rather than another period of dramatic appreciation. Realtor.com, for example, revised its 2026 forecast in July and projected existing-home prices to rise about 1.2% through the end of the year.
That does not mean every local market will experience the same result.
Some areas may see stronger price growth, while others may experience relatively flat prices or modest declines. Local inventory, demand, economic conditions, and property characteristics all play a role.
Inventory Can Influence Local Home Prices
The number of homes available for sale is an important factor to watch.
When inventory increases, buyers generally have more properties to compare. Sellers may also face greater competition, particularly when several similar homes are listed at the same time.
For buyers, increased inventory can create more opportunities to evaluate:
- Asking prices
- Property condition
- Recent comparable sales
- Price reductions
- Seller concessions
- Time on market
For sellers, understanding competing inventory can help with realistic pricing expectations.
Mortgage Rates Still Matter
Mortgage rates continue to influence purchasing power.
When borrowing costs are higher, buyers may adjust their budgets or focus more closely on monthly payments. Even when home prices remain relatively stable, changes in mortgage rates can affect what a buyer can comfortably finance.
This is why evaluating a home based solely on its listing price may not provide the complete affordability picture.
Buyers should consider the full cost of ownership, including principal and interest, property taxes, insurance, maintenance, and other applicable expenses.
Why Local Home Price Data Matters
A national median home price cannot tell you what a particular property is worth.
Even within the same city, prices can differ based on:
- Property type
- Square footage
- Lot size
- Property condition
- Age and construction
- Renovations and upgrades
- Location
- Current competing listings
Recent comparable sales can provide a much better reference point when evaluating a specific property.
Looking at active, pending, and recently sold properties together can also reveal how the market is changing.
What Buyers Should Watch
If you are considering buying a home in 2026, pay attention to more than the asking price.
Look at how long comparable properties have been on the market and whether sellers are making price adjustments. Review recent sales and compare the features and condition of similar properties.
It is also important to understand your financing options and establish a monthly budget that accounts for the complete cost of homeownership.
A lower-priced property is not automatically the least expensive option if it requires significant repairs or carries higher ongoing costs.
What Sellers Should Know
For sellers, accurate pricing is especially important in a market where buyers have more opportunities to compare properties.
An asking price that is significantly above recent comparable sales can limit initial buyer interest. On the other hand, pricing based on outdated information may not reflect current market conditions.
A current comparative market analysis can help evaluate:
- Recent comparable sales
- Active competition
- Pending listings
- Price changes
- Property condition
- Improvements
- Current market activity
The goal is to understand where a property fits within today’s market.
Looking Ahead Through 2026
The 2026 housing market continues to move toward a more balanced environment in many areas.
Home prices remain influenced by mortgage rates, inventory, buyer demand, and local economic conditions. National forecasts can help establish the broader picture, but hyper-local housing data is essential when making a decision about a specific property or market.
Whether you are monitoring home values, preparing to sell, or researching your next purchase, staying informed about local pricing trends can help you approach the market with a clearer perspective.
In real estate, knowing the local numbers can make all the difference.
by Lorena Cano | Sep 4, 2026 | Uncategorized
Real estate property management involves much more than collecting rent and responding to maintenance requests. Effective management requires organization, communication, financial planning, regular property care, and a clear understanding of day-to-day responsibilities.
Whether you own a single rental property or manage a larger portfolio, having reliable management practices can help protect the property, control operating costs, and support long-term performance.
What Is Real Estate Property Management?
Real estate property management is the process of overseeing the daily operations of a rental or investment property. Depending on the property and management agreement, responsibilities may include tenant communication, rent collection, maintenance coordination, financial tracking, inspections, marketing, and lease administration.
A well-organized approach can help property owners stay informed while ensuring important tasks are handled consistently.
Keep Property Maintenance on Schedule
Regular maintenance is one of the most important parts of property management. Small issues can become more expensive problems when they are overlooked.
Routine inspections and preventative maintenance can help identify potential concerns with plumbing, electrical systems, heating and cooling equipment, roofing, appliances, and other major components.
Keeping a maintenance schedule can also make expenses easier to plan and help preserve the property’s condition over time.
Maintain Clear Communication
Good communication can make property management more efficient. Property managers may communicate with owners, tenants, contractors, vendors, and other professionals throughout the management process.
Establish clear procedures for maintenance requests, property updates, payments, inspections, and other important matters. Keeping communication organized can reduce confusion and make it easier to resolve issues promptly.
Manage Property Finances Carefully
Financial management is another key part of successful property operations. Property owners need a clear understanding of rental income, operating expenses, maintenance costs, insurance, taxes, and other financial obligations.
Accurate records can help owners evaluate property performance and make informed decisions about repairs, improvements, and future investments.
Regular financial reviews can also help identify unnecessary expenses and potential opportunities to improve efficiency.
Use Technology to Improve Efficiency
Property management technology can simplify many routine responsibilities. Digital payment systems, property management software, maintenance platforms, accounting tools, and online communication systems can help organize information and reduce manual work.
Technology can also make it easier to track maintenance requests, store documents, monitor financial activity, and communicate important updates.
The best tools are those that fit the property’s needs and make daily operations easier to manage.
Understand Lease and Documentation Requirements
Accurate documentation is essential for property management. Leases, inspection records, maintenance requests, payment records, notices, and other documents should be organized and maintained securely.
Property owners and managers should also understand and follow applicable federal, state, and local laws. Because rental requirements can vary by location, consulting a qualified legal or housing professional when necessary can help reduce compliance risks.
Plan for Vacancies
Vacancies can affect rental property income, so having a clear leasing process is important.
When a property becomes available, management may involve preparing the property, determining appropriate marketing strategies, scheduling showings, reviewing applications, completing required documentation, and preparing for a new tenancy.
A consistent process can help reduce unnecessary delays while keeping each step organized.
Choose Vendors Carefully
Reliable contractors and service providers can make property management much easier. Property managers may rely on plumbers, electricians, HVAC professionals, landscapers, cleaning services, and other vendors.
Before selecting a vendor, consider experience, licensing where required, insurance, pricing, availability, and references. Maintaining good relationships with reliable vendors can also help improve response times when maintenance issues arise.
Protect the Property With Regular Reviews
Property management should include periodic reviews of the property’s condition and operating performance.
Review maintenance records, expenses, lease information, insurance coverage, and major systems regularly. These reviews can help identify issues before they become larger problems.
For investment properties, reviewing rental performance and operating costs can also help owners determine whether the current management strategy continues to support their financial goals.
Know When Professional Management May Help
Managing a property independently may work well for some owners. However, professional property management can be useful when responsibilities become difficult to manage.
A property management company may assist with tenant communication, maintenance coordination, rent collection, inspections, marketing, documentation, and other operational tasks.
The right choice depends on the owner’s time, experience, property type, location, budget, and management goals.
Build a More Efficient Management Strategy
Successful real estate property management is built on consistency. Regular maintenance, organized records, clear communication, careful financial management, and effective technology can create a stronger operating system for a property.
Whether you manage a rental property yourself or work with a professional manager, taking a proactive approach can help protect the property and support its long-term performance.
by Lorena Cano | Sep 2, 2026 | Uncategorized
Interest rates play an important role in the cost of borrowing money. For home buyers, even a small change in mortgage rates can affect monthly payments, purchasing power, and the total cost of a home loan.
Understanding how interest rates work can help buyers approach the mortgage process with a clearer financial plan.
What Is an Interest Rate?
An interest rate is the cost of borrowing money, expressed as a percentage of the loan amount. With a mortgage, the interest rate helps determine how much you will pay in interest over the life of the loan.
Mortgage rates can change based on economic conditions, inflation expectations, financial markets, lender pricing, loan type, and other factors.
How Interest Rates Affect Mortgage Payments
The interest rate on a mortgage directly affects the principal and interest portion of the monthly payment.
When rates are higher, borrowing the same amount generally results in a higher monthly payment. When rates are lower, the payment may be lower, assuming the loan amount and other terms remain the same.
For this reason, buyers should consider both the home price and the cost of financing when evaluating affordability.
Why Mortgage Rates Change
Mortgage rates can move for several reasons. Economic reports, inflation trends, employment conditions, financial market activity, and expectations about monetary policy can all influence borrowing costs.
Mortgage rates do not always move in the same direction or by the same amount as a central bank’s policy rate. Lenders consider several market factors when setting mortgage pricing.
Because rates can change over time, buyers should focus on their overall financial position rather than trying to predict every short-term movement.
Fixed-Rate and Adjustable-Rate Mortgages
Mortgage structure also matters when considering interest rates.
A fixed-rate mortgage generally keeps the interest rate unchanged for the agreed loan term. This can make monthly principal and interest payments more predictable.
An adjustable-rate mortgage, or ARM, may begin with a fixed rate for a specified period before the rate can adjust according to the terms of the loan.
Understanding how each loan works can help you evaluate the potential benefits, costs, and risks before choosing a mortgage.
Your Financial Profile Can Affect Your Rate
The rate available to a borrower may depend on several factors. Lenders may consider credit history, loan amount, down payment, loan type, property details, and other financial information.
This means two borrowers may receive different mortgage offers even when market rates are the same.
Improving your financial profile before applying for a mortgage may help you qualify for more competitive financing terms.
Look Beyond the Interest Rate
The interest rate is important, but it is not the only number that matters.
When comparing mortgage options, consider the annual percentage rate, loan fees, discount points, mortgage insurance, closing costs, monthly payment, and the total cost of borrowing.
A loan with a slightly lower rate may not always have the lowest overall cost if it comes with higher upfront fees.
Consider Your Long-Term Budget
A mortgage should fit within your broader financial plan. Before choosing a loan, consider your income, savings, monthly expenses, emergency reserves, and other financial obligations.
It is also important to account for costs beyond principal and interest, including property taxes, homeowners insurance, maintenance, and possible association fees.
A comfortable payment can provide more financial flexibility than simply choosing the maximum loan amount available.
Should You Wait for Lower Rates?
Trying to time the mortgage market can be difficult. Rates can move unexpectedly, and waiting for a lower rate may not always produce the outcome a buyer expects.
Instead of focusing entirely on where rates may go next, consider whether the home, payment, financing terms, and overall financial situation make sense today.
Future refinancing may be an option if market conditions and personal circumstances make it appropriate, but refinancing is never guaranteed.
Make Informed Mortgage Decisions
Interest rates are an important part of the home-buying equation, but they are only one piece of the larger financial picture.
Understanding how rates affect payments, comparing loan terms, reviewing the total cost of financing, and maintaining a realistic budget can help buyers make more informed decisions.
Working with a qualified mortgage professional can also help you understand current loan options and how they may fit your individual financial circumstances.
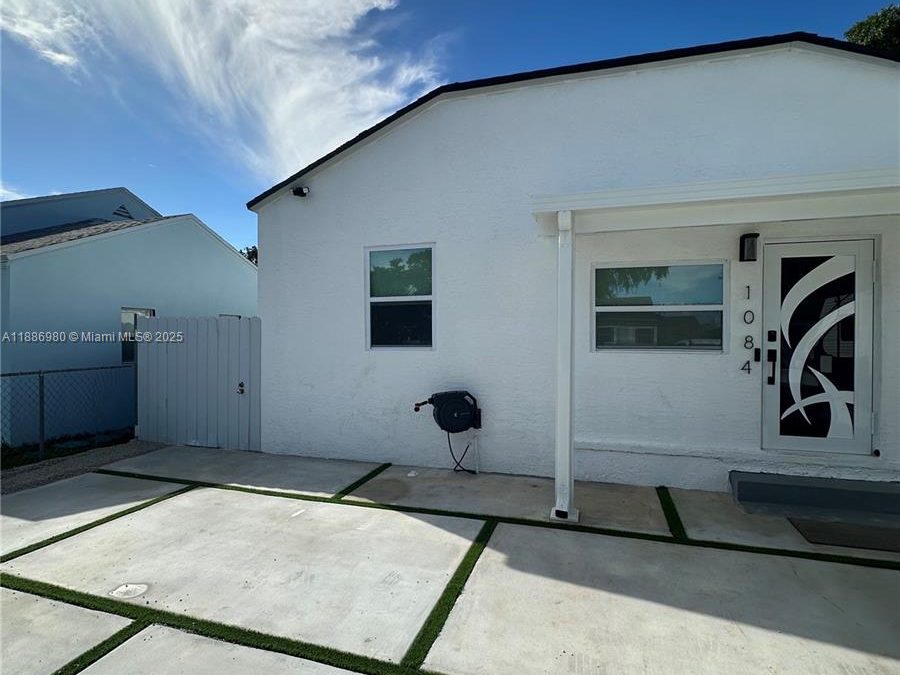
by Lorena Cano | Oct 18, 2025 | Residential Lease | Active

$1,650
Active
Brand new 1BD/1BA in the heart of it all! Private entrance, patio, in-unit washer & dryer, 2 parking spots, and ALL utilities included. Just 5 minutes to Midtown, Design District & Wynwood. Modern design, sleek finishes, and move-in ready today. Don’t miss it. It won’t last!
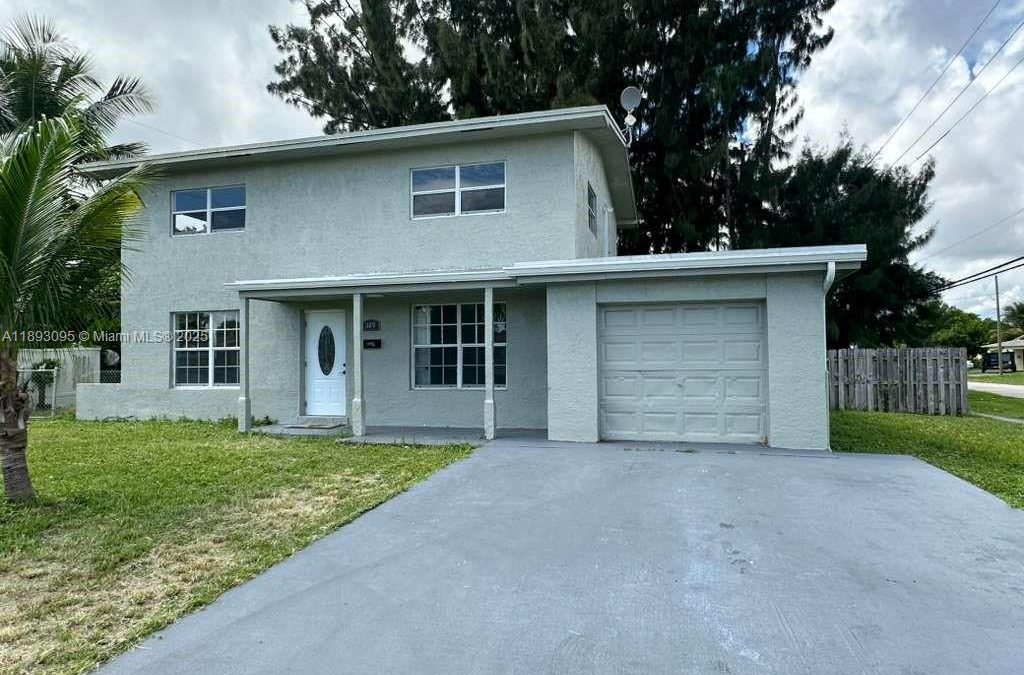
by Lorena Cano | Oct 9, 2025 | Residential Lease | Active

$3,950
Active
Beautifully renovated 5BD/2.5BA single-family home in the heart of Lauderhill! Move-in ready with modern finishes throughout, spacious living areas, and a stunning kitchen with stainless steel appliances. Features a walk-in closet, large windows with natural light, and a huge fenced backyard. Perfect for relaxing or entertaining in a quiet, family-friendly neighborhood. Conveniently located near schools, parks, shopping, and major highways. Don’t miss this opportunity!
by Lorena Cano | Sep 16, 2025 | Property Management
Real estate investment can provide passive income, tax benefits, and long-term wealth-building opportunities. However, successful property investment requires market knowledge, financial planning, and ongoing management commitment.
Types of Investment Properties: Single-family rental homes offer simplicity and broad tenant appeal but require hands-on management. Multi-family properties provide multiple income streams and economies of scale but involve more complex management. Commercial properties can offer higher returns but require substantial capital and market expertise. REITs (Real Estate Investment Trusts) allow real estate investment without direct property ownership.
Financial Considerations: Investment property financing typically requires higher down payments (20-25%) and slightly higher interest rates than primary residences. Calculate all costs, including purchase price, renovation needs, property management, insurance, taxes, maintenance reserves, and vacancy allowances. The 1% rule suggests monthly rent should equal at least 1% of the purchase price, though this varies by market.
Location Analysis: Successful rental properties are located in areas with strong employment, population growth, good schools, and amenities. Proximity to universities, hospitals, or major employers can provide steady tenant demand. Research neighborhood trends, crime statistics, and future development plans that might impact property values and rental demand.
Cash Flow vs. Appreciation: Some investors prioritize immediate cash flow through rental income, while others focus on long-term appreciation potential. Cash flow properties provide monthly income but may be in slower-growth areas. Appreciation-focused investments might require subsidizing monthly costs but offer greater long-term wealth-building potential.
Tax Benefits: Real estate investment offers several tax advantages, including depreciation deductions, mortgage interest deductions, property tax deductions, and the ability to defer capital gains through 1031 exchanges. Consult with tax professionals to understand and maximize these benefits.
Property Management: Decide whether to self-manage or hire professional property management companies. Self-management offers higher returns but requires time for tenant screening, rent collection, maintenance coordination, and legal compliance. Professional management typically costs 8-12% of rental income but provides expertise and time savings.
Tenant Screening: Quality tenants protect your investment through timely rent payments and property care. Develop consistent screening criteria, including credit scores, income verification, employment history, and references. Understand fair housing laws to ensure compliance during the selection process.
Market Research: Analyze local rental markets to understand competitive rent levels, typical vacancy rates, and tenant preferences. This information helps optimize your investment strategy and property improvements.
Risk Management: Diversify investments across different property types or locations to minimize risk. Maintain adequate insurance coverage and emergency reserves for unexpected repairs or extended vacancies. Stay informed about landlord-tenant laws and market conditions.
Exit Strategies: Consider your long-term plans: Will you hold properties indefinitely for income, sell for appreciation gains, or transition to more passive investments like REITs? Having clear exit strategies helps guide investment decisions and timing.
Real estate investment can build significant wealth over time, but success requires education, planning, and often professional guidance to navigate the complexities effectively.
by Lorena Cano | Sep 16, 2025 | Secure Financing
In competitive real estate markets, desirable properties often receive multiple offers, sometimes selling above asking price within days of listing. Success requires preparation, speed, and strategic thinking to stand out among competing buyers.
Pre-Purchase Preparation: Get fully pre-approved for your mortgage, not just pre-qualified. Pre-approval demonstrates serious buyer intent and financial capability to sellers. Organize all necessary documentation in advance so you can move quickly when you find the right property. Consider getting pre-approved for slightly more than your target budget to provide negotiating flexibility.
Working with the Right Agent: Choose an agent with extensive experience in competitive markets and strong relationships with local listing agents. They should be available to show properties quickly, have intimate knowledge of neighborhoods and pricing trends, and possess excellent negotiation skills. Their reputation and relationships can be crucial advantages.
Setting Realistic Expectations: Understand that you may not get the first property you offer on, and that’s normal in competitive markets. Prepare mentally and financially for the possibility of offering above the asking price. Define your absolute maximum budget beforehand to avoid emotional overspending during bidding wars.
Speed and Flexibility: Be prepared to view properties immediately when they hit the market. Have your schedule flexible for short-notice showings and be ready to make decisions quickly. Sometimes properties sell before scheduled open houses, so private showings become essential.
Crafting Compelling Offers Strong offers often exceed the asking price, but price isn’t everything. Consider offering shorter inspection periods, flexible closing dates that work for sellers, or waiving certain contingencies if you’re comfortable with the risks. Larger earnest money deposits demonstrate commitment and financial strength.
Appraisal Strategies. In competitive markets, winning offers often exceed appraised values. Consider including appraisal gap coverage, agreeing to pay a certain amount above appraised value if necessary. This shows sellers you’re committed even if the property doesn’t appraise for the full purchase price.
Personal Connections Sometimes personal letters to sellers help your offer stand out, though this practice is becoming less common due to fair housing considerations. Focus on what you love about the property and how you’ll care for it rather than personal details about your family situation.
Backup Offers Don’t overlook properties that are already under contract. Submitting backup offers can position you to purchase if the primary offer falls through, which happens more frequently than many buyers realize.
Alternative Strategies: Consider properties that have been on the market longer or need cosmetic improvements. These may face less competition while still meeting your needs. Off-market properties identified through your agent’s network can provide opportunities without competition.
Managing Emotions: Competitive markets can be emotionally exhausting. Maintain perspective and remember that the right property will come along. Don’t compromise your financial stability by overstretching your budget due to market pressure.
Post-Offer Strategy Once your offer is accepted, move quickly on inspections and financing to avoid delays that might jeopardize the transaction. Maintain good communication with sellers and be responsive to any requests or negotiations.
Success in competitive markets requires preparation, realistic expectations, and often some patience. With the right strategy and professional guidance, you can successfully navigate challenging market conditions.
by Lorena Cano | Sep 16, 2025 | Downsizing Checklists
Life transitions often prompt housing changes, and downsizing can offer financial benefits, reduced maintenance responsibilities, and lifestyle improvements. However, moving from a longtime family home requires careful planning and emotional preparation.
Recognizing the Right Time: Common triggers for downsizing include children leaving home, retirement, health changes, or a desire for lifestyle simplification. Financial motivations might include reducing housing costs, accessing home equity, or eliminating maintenance burdens. The decision should align with your long-term goals and current life circumstances.
Choosing Your Next Home: Consider what matters most in your next chapter. Many downsizers prioritize single-level living, low-maintenance exteriors, proximity to healthcare and amenities, and community features. Active adult communities offer social opportunities and maintenance-free living, while urban condos provide walkability and cultural attractions. Some prefer staying in familiar neighborhoods in smaller homes.
Financial Planning: Downsizing can free up significant equity, but consider the complete financial picture. Factor in moving costs, potential capital gains taxes, new homeowner association fees, and different utility costs. Consult with financial advisors and tax professionals to understand implications and optimize your strategy.
Decluttering Strategies: Reducing possessions accumulated over decades can feel overwhelming. Start early and tackle one room at a time. Sort items into categories: keep, donate, sell, or discard. Consider which items truly add value to your life and which hold only sentimental attachment. Family members might appreciate heirloom pieces, while donation organizations benefit from usable items.
Emotional Considerations: Leaving a home filled with memories can be emotionally challenging. Acknowledge these feelings as natural and give yourself time to process the change. Focus on the positive aspects of your move: new adventures, reduced responsibilities, and fresh starts. Consider creating photo albums or memory books to preserve special moments from your current home.
Timing the Move: Coordinate the sale of your current home with your new home purchase. Some choose to rent temporarily to allow adequate time for house hunting without pressure. Others prefer simultaneous closings to avoid double housing costs. Your real estate professional can help develop a timeline that minimizes stress and financial impact.
Professional Support Experienced real estate agents understand downsizing challenges and can recommend resources like estate sale companies, senior move managers, contractors for home preparations, and other helpful services. These professionals can streamline the process significantly.
Maintenance and Lifestyle Benefits Smaller homes typically require less maintenance, cleaning, and utility costs. This frees up time and money for travel, hobbies, and other interests. Many downsizers discover they feel liberated by owning fewer possessions and maintaining simpler lifestyles.
Successful downsizing requires planning, patience, and the right professional support. When approached thoughtfully, it can enhance your quality of life while providing financial benefits for your retirement years.
by Lorena Cano | Sep 6, 2025 | Economy
September 2025 – Mortgage delinquencies in the United States are rising, albeit gradually, signaling a possible shift in the stability of the housing market. While current levels remain below historical averages, recent data reveal emerging signs of financial strain—particularly among FHA and VA loan holders—that could lead to a surge in foreclosures if not addressed.
Mortgage Delinquencies Are Creeping Up
According to the Mortgage Bankers Association (MBA), the overall mortgage delinquency rate reached 3.93% in Q2 2025, down slightly from 4.04% in Q1 but still elevated compared to last year. Although this remains well below the long-term average of around 5.2%, the rise in serious delinquencies (loans 90+ days past due or in foreclosure) is catching the attention of market analysts.
Notably, early-stage delinquencies—borrowers just beginning to miss payments—have started climbing in several categories, signaling potential future risks.
FHA and VA Loans Show Warning Signs
Borrowers with FHA and VA loans are experiencing significantly higher delinquency rates than those with conventional loans. These government-backed loans are typically issued to first-time buyers and veterans—groups more vulnerable to economic stress.
- FHA loans: Delinquency rates have remained above 10%, with recent reports placing them at 10.57% in Q2 2025.
- VA loans: Though somewhat more stable, VA delinquencies also remain elevated, at 4.32% as of mid-2025.
Compounding this issue is the expiration of the Veterans Affairs Servicing Purchase (VASP) program in May 2025. The VASP helped thousands of struggling veteran homeowners avoid foreclosure by allowing VA to purchase delinquent loans from servicers. With the program no longer available, VA foreclosure inventory has surged to 0.84%—its highest level since 2019.
What This Means for Foreclosures
The uptick in mortgage delinquencies doesn’t yet signal a foreclosure crisis, but the trend is worth watching closely. Here’s what it could mean going forward:
1. Targeted Foreclosure Risks Are Rising
Foreclosure starts are still low overall (0.20% in Q1 2025), but certain borrower segments—particularly FHA and VA—are showing signs of growing stress. Without proactive intervention, this could translate into higher foreclosure rates in late 2025 and 2026.
2. Overall Housing Market Still Resilient
Thanks to steady employment levels and substantial homeowner equity, the broader housing market remains stable. However, early-stage delinquency increases and rising consumer debt levels may expose weaknesses beneath the surface.
3. Policy Gaps Could Exacerbate Problems
The end of the VASP program leaves a gap in foreclosure prevention tools for veterans. Without a replacement or new mitigation policies, foreclosures in this segment could spike sharply, setting off localized impacts in areas with high concentrations of VA loans.
4. Consumer Financial Fragility Is Growing
Data also show rising delinquencies in other areas—such as auto loans and credit cards—which often precede mortgage stress. This points to broader financial pressure on households that could spill into the housing market in the coming quarters.
Looking Ahead
While a national foreclosure crisis like the one seen in 2008 is unlikely, the recent data underline the importance of monitoring regional and demographic-specific risks. Policymakers and lenders may need to expand loss mitigation tools, especially for FHA and VA borrowers, to prevent an avoidable wave of foreclosures.
For homeowners, it’s a reminder to stay vigilant with finances, and for investors, a reason to watch the market’s lower end more closely.
Bottom Line:
Mortgage delinquency rates remain manageable overall, but warning signs are flashing—especially among first-time and lower-income borrowers. Unless addressed with policy support and borrower assistance, these signs could evolve into a rise in foreclosures over the next year.
by Lorena Cano | Aug 28, 2025 | Housing Market Update
If you’ve been browsing homes this summer, you’re not alone and you’re likely seeing more options than you did a year ago. But while inventory is up, buyers are taking their time, and sellers are starting to feel the pressure.
According to Realtor.com’s latest housing trends report, the U.S. real estate market is shifting into a slower, more buyer-friendly phase. Here’s what that means for you.
More Homes on the Market
According to Realtor.com, the number of homes for sale continues to climb, with active listings up 24.4% compared to this time last year, marking the 89th straight week of inventory growth, and for the 11th week in a row, there are over 1 million homes available nationwide something we haven’t seen since 2019.
Homes Are Sitting Longer
The typical home now spends 58 days on the market, which is one day longer than the same week in July 2019. That’s a clear sign that buyers are being more cautious and taking their time before making offers.
Price Cuts Are on the Rise
With homes lingering longer, sellers are adjusting. In June, 1 in 5 homes had a price reduction the highest rate for that month in Realtor.com’s records. While overall list prices are still slightly up year-over-year, the growing number of price cuts suggests sellers are responding to softer demand.
Mortgage Rates Are Still a Hurdle
The average 30-year fixed mortgage rate ticked up to 6.75%, making monthly payments more expensive and keeping some buyers on the sidelines. Even so, mortgage applications rose slightly, showing that some buyers are still testing the waters.
What This Means for You
- Buyers: You’ve got more choices and more negotiating power than you did a year ago. If you’ve been waiting for the market to cool, this could be your moment especially if you’re flexible on timing or location.
- Sellers: It’s still a good time to sell, but pricing your home right is more important than ever. Homes that are priced competitively and show well are still moving, but patience may be required.
by Lorena Cano | Aug 28, 2025 | Security Taxes
If you’ve been following the headlines, you may have heard that President Trump’s newly signed “One Big Beautiful Bill Act” (OBBB) has eliminated taxes on Social Security benefits. That’s a bold claim—and one that’s stirred up a lot of confusion, especially among retirees and those planning for retirement. So, what’s going on?
Let’s break it down in plain English.
The Promise vs. The Reality
During his campaign, President Trump promised to eliminate taxes on Social Security benefits. With the passage of the OBBB on July 4, 2025, the White House declared that promise fulfilled, stating there would be “NO tax on Social Security.”
But here’s the catch: financial experts say the bill doesn’t actually change how Social Security is taxed.
Instead, the bill introduces a temporary bonus deduction for seniors—an extra tax break that could reduce or even eliminate the taxes some retirees pay on their Social Security benefits. But this is not the same as removing the tax altogether.
What Is the Bonus Deduction?
The OBBB includes a $6,000 additional deduction for individuals aged 65 and older. For married couples filing jointly, that’s a $12,000 deduction. This deduction is available for tax years 2025 through 2028.
This means that if you’re 65 or older, you can subtract an extra $6,000 (or $12,000 for couples) from your taxable income. That could lower your overall tax bill—and in some cases, reduce the amount of your Social Security benefits that are taxed.
But—and this is important—the deduction is not tied directly to Social Security. You don’t need to be receiving Social Security to claim it. You just need to meet the age and income requirements.
So, Are Social Security Benefits Still Taxed?
Yes. The rules for taxing Social Security benefits haven’t changed. Depending on your income, up to 85% of your Social Security benefits may still be taxable.
The new deduction might help offset that tax for some people, but it doesn’t eliminate it. As financial advisor Martin Baker puts it, “It doesn’t have a direct impact on Social Security.”
What This Means for You
If you’re a retiree—or planning to retire soon—this new deduction could be a welcome tax break. It might mean more money in your pocket, especially if your income is modest.
However, it’s important to understand that this is a temporary measure. The deduction only applies from 2025 through 2028. After that, unless Congress acts again, it will disappear.
Also, because the deduction isn’t specifically tied to Social Security, it doesn’t guarantee that your benefits will be tax-free. Your total income still plays a big role in determining how much of your Social Security is taxed.
Final Thoughts
The One Big Beautiful Bill Act may sound like a sweeping change to Social Security taxes, but in reality, it’s more of a clever workaround than a true overhaul. It offers a helpful deduction for seniors, but it doesn’t rewrite the rules on how Social Security is taxed.
If you’re unsure how this affects your personal tax situation, it’s a good idea to speak with a tax advisor or financial planner. They can help you understand how to make the most of the new deduction—and how to plan for what comes next.
by Lorena Cano | Aug 28, 2025 | Apartment Essentials
Whether you’re moving into your first apartment or upgrading to a new space, 2025 brings a fresh wave of must-have items and smart upgrades that make apartment living more comfortable, efficient, and stylish. From tech-savvy tools to timeless basics, here’s your go-to guide for apartment essentials this year.
1. Smart, Space-Saving Furniture
With more people working and living in smaller spaces, multi-functional furniture is a top priority. Think:
- Fold-out desks for hybrid work setups
- Storage ottomans and under-bed bins
- Modular sofas that adapt to your layout
These pieces help maximize square footage without sacrificing style.
2. Smart Home Devices
Tech continues to transform apartment living. In 2025, renters are embracing:
- Smart plugs and voice-controlled lighting
- Wi-Fi-enabled thermostats (if your lease allows)
- Video doorbells or smart locks for added security
These upgrades are renter-friendly and easy to take with you when you move.
3. Compact Laundry Solutions
Not every apartment has in-unit laundry, but that doesn’t mean you’re stuck. Popular options include:
- Portable washers that hook up to your sink
- Drying racks that fold away when not in use
- Laundry carts for easy trips to the building’s laundry room
4. Indoor Plants & Air Quality Boosters
Greenery is still in. In fact, indoor plants are now considered part of the wellness toolkit. Add:
- Low-maintenance plants like snake plants or pothos
- A compact air purifier to reduce allergens and odors
- Aromatherapy diffusers for a calming vibe
5. Organizational Must-Haves
Clutter-free living is key in 2025. Trending tools include:
- Clear storage bins for closets and pantries
- Over-the-door organizers for shoes, cleaning supplies, or toiletries
- Magnetic spice racks and stackable containers for small kitchens
6. Energy-Efficient Lighting
LED lighting is now the standard, but renters are also opting for:
- Smart bulbs with adjustable color temperatures
- Clip-on or plug-in sconces for extra lighting without hardwiring
- Motion-sensor night lights for hallways and bathrooms
7. Temporary Decor That Feels Permanent
Just because you’re renting doesn’t mean you can’t personalize your space. Try:
- Peel-and-stick wallpaper or backsplash tiles
- Command hooks and strips for art and shelving
- Area rugs to define spaces and add warmth
Final Thoughts
Apartment living in 2025 is all about efficiency, comfort, and personalization. Whether you’re staging a rental for potential tenants or helping a client settle into their new space, these essentials can make a big difference in how a home feels—and functions.
by Lorena Cano | Aug 28, 2025 | Education Strategy
College tuition costs have skyrocketed in recent years, and families across the country are getting creative to manage the financial burden. One surprising strategy gaining traction? Buying a home in the state where your child plans to attend college.
It might sound extreme, but the math checks out. Public universities typically offer steep discounts to in-state residents—sometimes cutting tuition by more than half. And for families with multiple children heading to college, those savings can add up fast.
Why It Works
Every state offers lower tuition rates to residents. The logic is simple: residents pay taxes that help fund public universities, so they get a break on tuition. For example, the average out-of-state tuition for a four-year public university is around $28,297, while in-state students pay just $9,750.
Even at top-tier schools, the difference is dramatic. Take the University of Florida: out-of-state students pay about $28,658 per year, while in-state students pay just $6,380 a a discount of 77% discount.
Real Estate Meets Education Strategy
Some families are taking advantage of this by purchasing property in states with generous in-state tuition policies. In places like Texas, Florida, and Connecticut, the savings can be substantial enough to offset the cost of buying a home.
Houston-based real estate agent Erwin Nicholas says education is a major driver for his clients. “Pretty much all of my clients are moving to Texas with education-based decisions in mind,” he told Realtor.com [1]. With Texas offering an average 67% tuition discount for residents, it’s easy to see why.
What to Consider Before You Buy
Of course, buying property isn’t a decision to take lightly. Homes come with their costs—think HOA fees, insurance, maintenance, and property taxes. And residency requirements vary by state and university, so it’s important to do your homework.
Still, for families who are already considering a move or have long-term plans in a particular state, this strategy could be a smart financial move. Over four years (or more, if you have multiple kids), the savings could easily cover the cost of the home.
Final Thoughts
If you’re planning for college and looking for ways to cut costs, exploring in-state tuition opportunities through real estate might be worth a closer look. Just be sure to crunch the numbers and consult with a local real estate expert and university admissions office to understand the residency rules.